Quick Answer
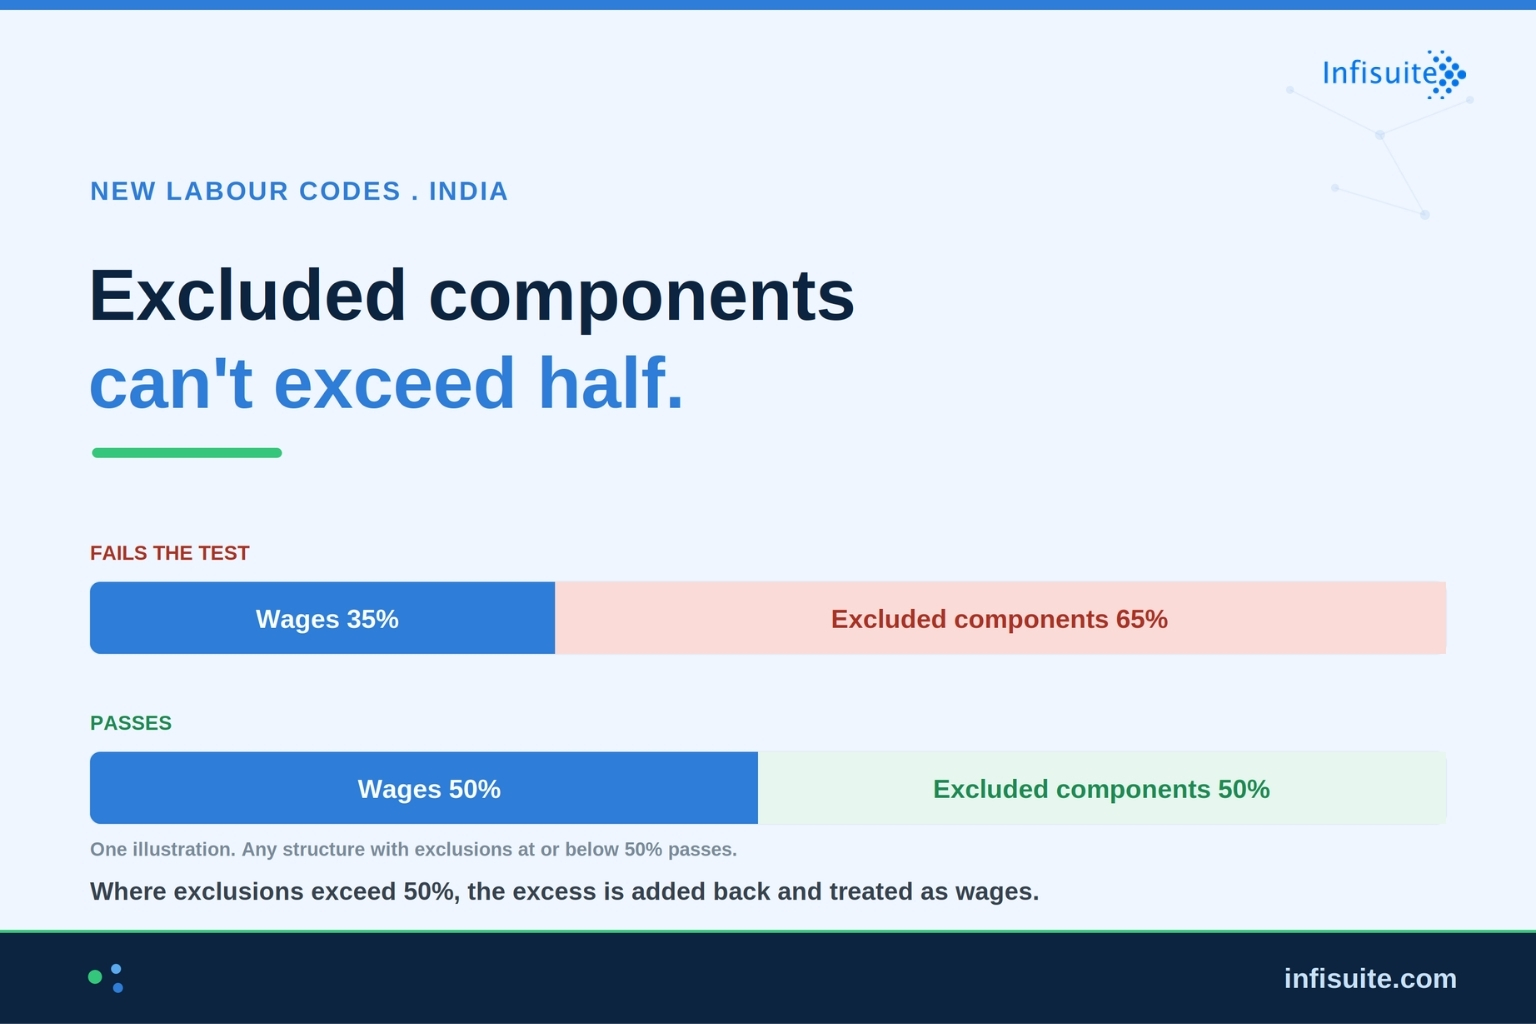
The 50% wage rule comes from the Code on Wages, 2019. Specified components excluded from wages cannot exceed 50% of an employee's total remuneration. If they do, the excess is added back and treated as wages for statutory calculations.
The rule does not mean basic pay must always be exactly 50% of CTC. The four Labour Codes came into force on 21 November 2025, and the Ministry of Labour and Employment has confirmed the revised wage definition applies from that date.
Key Takeaways
- The rule is about exclusions, not basic pay. Specified excluded components cannot exceed 50% of remuneration.
- Any excess is added back to wages. If exclusions come to 65%, the excess 15% joins the wage base.
- Basic pay does not have to be exactly 50%. Employers can structure remuneration in different ways as long as the statutory test is satisfied.
- PF and gratuity costs can increase where the applicable wage base rises.
- Overtime allowance counts in the calculation, according to the Ministry's FAQ.
- Annual performance-based incentives do not form part of wages for Labour Code calculations.
- Wages payable on exit must be paid within two working days.
- State-specific requirements still matter. Check the rules applicable to your establishment, sector and state.
A common approach to salary structuring in India has been to keep basic pay relatively low and spread the rest of the package across allowances such as HRA, conveyance and special allowance.
The Labour Codes change how wages are defined for statutory purposes.
On 21 November 2025 the four Labour Codes came into force, replacing 29 central labour laws. The Code on Wages, 2019 matters most for payroll, because it establishes a common definition of wages.
The important point is this. The rule does not simply say that basic pay must be 50% of CTC. It identifies specified exclusions, and provides that when those exclusions exceed 50% of remuneration, the excess is added back into wages.
What Changed in the Definition of Wages
The Code on Wages starts with the remuneration payable to an employee, then specifies which components are included in wages and which are excluded.
Included at the core:
- Basic pay
- Dearness allowance
- Retaining allowance
Excluded, subject to the conditions in the definition:
- House rent allowance
- Conveyance allowance
- Overtime allowance
- Commission
- Bonus payable under applicable law
- Employer contribution to provident fund or pension
- Value of certain benefits such as accommodation
- Travelling allowance or travel concession
- Amounts paid to defray special expenses
- Gratuity payable on termination
- Retrenchment compensation and other termination benefits
The practical point for payroll teams is that an item being called an "allowance" does not automatically mean it sits outside wages. The statutory definition has to be applied component by component.
Two Important Ministry Clarifications
Overtime counts in the calculation
The Ministry's FAQ states that overtime allowance forms part of the relevant components. Where the applicable exclusions exceed 50% of remuneration, the excess is added to wages.
This matters most for businesses where overtime is a significant part of employee earnings, because it can push exclusions past the threshold without anyone planning it.
Annual performance-based incentives are treated differently
The Ministry has clarified that annual performance-based incentives do not form part of wages for computation under the Labour Codes.
That distinction matters in practice. A genuine performance-linked variable payment should not be treated the same way as a fixed salary component simply because both appear under "incentives" in the payroll system.
Read the Ministry's Labour Codes FAQs
The 50% Wage Rule, Explained Properly
The rule is usually simplified to "basic pay must be 50% of CTC." That is not the test.
The test applies to the excluded components. If specified exclusions exceed 50% of remuneration, the excess is added back and treated as wages.
Excess added back = specified exclusions − 50% of remuneration
If the result is zero or negative, there is nothing to add back. If it is positive, that excess increases the wage base.
A worked example
Take an employee with annual remuneration of ₹10,00,000, structured with basic pay at 35%.
| Step | Calculation | Amount |
|---|---|---|
| Total remuneration | — | ₹10,00,000 |
| Excluded components | 65% of remuneration | ₹6,50,000 |
| Permitted exclusion | 50% of ₹10,00,000 | ₹5,00,000 |
| Excess added back | ₹6,50,000 − ₹5,00,000 | ₹1,50,000 |
| Wage base | ₹3,50,000 basic + ₹1,50,000 add-back | ₹5,00,000 |
The employee's basic pay on the payslip is ₹3,50,000. The wage base used for statutory calculations is ₹5,00,000.
That gap is the whole point. An employer looking only at the basic pay percentage would calculate PF on ₹3,50,000 and be wrong.
One way to remove the gap is to restructure so basic pay is 50% and exclusions sit at the limit. That is a practical approach, not a legal requirement. The law does not oblige every employee to have basic pay at exactly half of CTC.
What This Costs
Several statutory calculations use wages as their base. When that base increases, the resulting amounts increase too.
Provident fund
For EPF-covered employees, the standard contribution is generally 12% from the employee and 12% from the employer on applicable wages. Statutory ceilings, special categories and higher-wage arrangements can affect the actual calculation.
So the contribution rate does not become higher. The wage base it applies to does.
Contribution rules and filing requirements are administered by the Employees' Provident Fund Organisation. For the broader picture on PF, ESI and TDS obligations, see our guide to payroll compliance in India.
Gratuity
Gratuity is calculated on the applicable wage basis, so a higher wage base means a higher payout on exit and a higher liability carried on the books today.
The Ministry's FAQ confirms that the revised wage definition applies to gratuity from 21 November 2025. For an employer with several hundred employees, even a modest increase in the wage base creates a significant additional liability, because it moves for everyone at once.
Employees' State Insurance
ESI calculations and coverage depend on their own statutory provisions and wage thresholds. Current requirements are published by the Employees' State Insurance Corporation.
The point worth making here is that each statutory obligation has its own rules. Applying the PF logic to everything produces the wrong answer.
Impact on employees
Where total compensation stays broadly unchanged but the wage component increases, employee deductions such as PF also increase. Monthly take-home pay can fall slightly while statutory retirement savings rise.
That is why the change needs explaining before the first altered payslip reaches anyone.
What Else Changed
Exit payments: two working days
Under the Code on Wages, wages payable to an employee who has been removed, dismissed, retrenched or has resigned must be paid within two working days.
This is more precise than calling it a 48-hour full-and-final settlement. A final settlement can involve final wages, leave-related payments, notice pay, gratuity, recoveries, advances, assets and tax treatment. Each component is handled under the provision applicable to it.
Operationally, though, the effect is the same: payroll and HR need a much faster exit process. It is the exit end of the hire-to-retire payroll cycle, and the point where manual processes usually fail.
Fixed-term employees and gratuity
The framework provides gratuity for eligible fixed-term employees after one year of service, rather than the continuous-service requirement that applies to permanent employees.
Because transitional and employment-specific facts matter, verify the treatment for employees already in service when the Codes came into force.
Four-day work week
The OSH framework allows flexibility in how weekly working hours are distributed, which is why the Codes are often described as permitting a four-day week.
That is not a universal right to schedule every employee for four twelve-hour days. Weekly hour limits, rest requirements, overtime provisions and establishment-specific rules all still apply. The practical question is not "can we work four days" but "can our proposed roster comply with the applicable working-hour, overtime, rest and state requirements."
Appointment letters
The Codes strengthen the requirement for employees to receive appointment documentation setting out the terms of employment. Informal offer letters and verbal arrangements are no longer sufficient.
Minimum wage coverage
The Code on Wages widens the minimum wage framework beyond the narrower scheduled-employment approach that applied previously.
Gig and platform workers
The Code on Social Security creates a framework for social-security coverage of gig and platform workers. Detailed contribution and scheme requirements depend on the applicable notifications.
Where the Rules Currently Stand
The four Labour Codes came into force on 21 November 2025. The Ministry's notification brought the relevant provisions of the Code on Wages into force from that date.
The Ministry's FAQs confirm that the wage definition applies from 21 November 2025, that the revised definition applies to gratuity from the same date, that overtime allowance is included in the relevant calculation, that excess exclusions above 50% are added back to wages, and that annual performance-based incentives do not form part of wages.
The full text of the Code on Wages, 2019 is available on the India Code portal.
Because labour is a concurrent subject, employers still need to check the rules applicable to their establishment, sector and state. A single implementation checklist does not answer every state-specific requirement.
What to Do Now
1. Run the 50% test across payroll. For every employee, identify the applicable excluded components and compare the total against 50% of remuneration. Do not assume an item is excluded because it is called an allowance.
2. Model the financial impact. Calculate the effect on employee PF, employer PF, gratuity liability, other wage-linked statutory costs and take-home pay. Do this before changing anything.
3. Decide how to absorb it. The employer can absorb the additional statutory cost or restructure remuneration while keeping the overall package intended. Either way, model the employee-level effect first.
4. Explain the change to employees. A payslip that suddenly shows a different basic pay, PF deduction or net salary creates confusion. People should understand what changed, why, and what happens to take-home pay, PF and gratuity.
5. Update the payroll system. Salary templates, wage definitions, contribution formulas and statutory calculations all need to reflect the new basis. This is the step that gets forgotten, and it causes wrong deductions from the first run.
6. Rework the exit process. If HR, attendance, leave, payroll and finance data sit in different systems, completing exit calculations within two working days becomes difficult. Work out what your current process actually takes.
Why This Is Harder on Spreadsheets
The calculation itself is not difficult. Doing it accurately for every employee, every payroll cycle, while maintaining attendance, leave, reimbursements and statutory deductions, is the harder part.
A salary restructure touches the employee master, attendance, leave, overtime, payroll, PF, ESI, TDS, gratuity and accounting. If those live in separate files, every change has to be carried across by hand.
The two-working-day requirement makes it sharper still. A final wage calculation may need information from HR, attendance, leave, payroll and finance, all agreeing with each other, inside two days. That is achievable when the data sits in one place. It is not when someone has to request figures from three departments first.
This is often the point at which businesses find they have outgrown spreadsheets for payroll.
When payroll runs on a connected system, the wage definition is configured once and the applicable deductions calculate automatically. That is what the Infisuite HR & Payroll module is designed to support.
Frequently Asked Questions
What is the 50% wage rule?
Under the Code on Wages, specified excluded components cannot exceed 50% of remuneration for the wage calculation. If the applicable exclusions exceed 50%, the excess is added back to wages.
Does basic pay have to be exactly 50% of CTC?
No. The test applies to the excluded components, not to basic pay itself. A 50% basic pay structure is one way of restructuring remuneration, but it is not the rule itself.
When did the Labour Codes come into force?
The four Codes came into force on 21 November 2025, and the Ministry's FAQ confirms the revised wage definition took effect from that date. Employers should also check the rules applicable to their establishment, sector and state.
Which components count as wages?
Basic pay, dearness allowance and retaining allowance form the core of the definition, subject to the statutory exclusions. Not every other salary component is automatically excluded simply because it is called an allowance.
Will my take-home pay go down?
It may, depending on how the structure changes and how the applicable PF contribution is calculated. A higher employee PF contribution reduces monthly take-home pay while increasing retirement savings.
Do PF and gratuity costs increase for employers?
They can, where the applicable wage base increases. The exact impact depends on the employee's remuneration structure and the provisions applicable to the employer.
What changed for fixed-term employees?
Eligible fixed-term employees qualify for gratuity after one year of service, subject to the applicable provisions. Permanent employees remain subject to the continuous-service requirements.
What is the two-working-day settlement rule?
The Code on Wages requires wages payable on termination to be paid within two working days. This is distinct from the treatment and timing of other components that may form part of a full-and-final settlement.
Does overtime count towards the 50% calculation?
Yes. The Ministry's FAQ states that overtime allowance is included in the relevant calculation, and that excess over the 50% limit is added to wages.
Are annual performance bonuses treated as wages?
No. Annual performance-based incentives do not form part of wages for Labour Code calculations. The treatment should still reflect the actual nature of the payment rather than the label used in the payroll system.
Do we have to restructure salaries immediately?
The revised definition is already in force. Practical compliance requirements can depend on the establishment, sector and state rules, so model the impact and verify your position before implementing changes.
Conclusion
The 50% wage rule is a change of base, not a change of rate. Contribution percentages stay where they were. What moves is the figure they are applied to.
For employers that can mean higher PF costs, a higher gratuity liability, changes to employee take-home pay, salary structures that need review, and more pressure on payroll and exit processes.
The practical sequence is straightforward. Model the cost first. Update the payroll system. Then explain the change clearly to employees, before the first altered payslip lands.
Need your payroll to reflect the new wage definition?
Model salary restructuring, payroll calculations and statutory impact before implementation.
Written by Anjana A
ERP & Business Software Specialist, Infisuite
Anjana A writes about ERP, HR operations and business automation for growing SMEs. She focuses on clear, practical guidance that helps businesses stay compliant and run their people operations without unnecessary complexity.
This article is general information, not legal or tax advice. Labour Code requirements can depend on the applicable provisions, establishment, sector and state. Confirm the current position with your professional advisor before restructuring salaries.